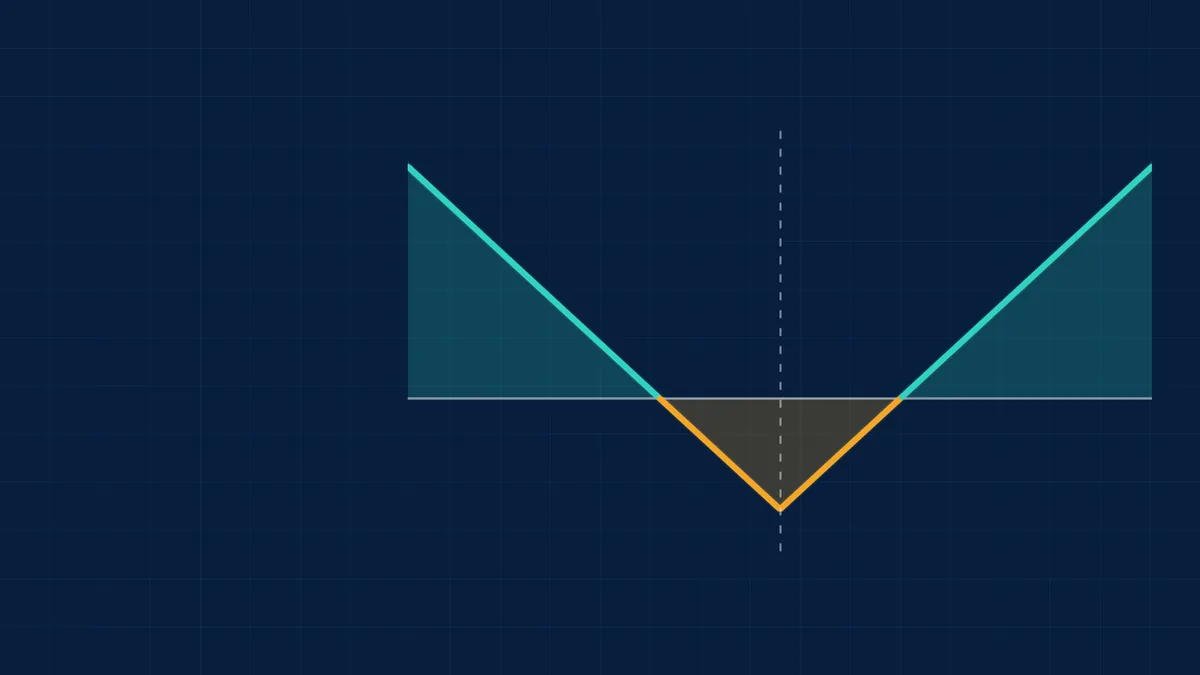
A long straddle buys a call and a put on the same underlying, with the same strike and expiry. It makes money if price moves far enough in either direction, and loses if price stays near the strike. It is a bet on a large move, not on its direction.
How it is built
- Buy one call at the strike (normally at the money).
- Buy one put at the same strike and expiry.
- The total premium paid is the cost and the maximum loss.
See what markets are pricing in
Live indices, sector moves and market breadth — the backdrop to every story we publish.
A worked example
The Nifty is at 24,000. A trader buys the 24,000 call for 150 and the 24,000 put for 140.
| Item | Calculation | Result |
|---|---|---|
| Total premium (max loss) | 150 + 140 | 290 points, if the Nifty expires at 24,000 |
| Upper breakeven | 24,000 + 290 | 24,290 |
| Lower breakeven | 24,000 - 290 | 23,710 |
| Profit at expiry of 24,500 | (24,500 - 24,000) - 290 | 210 points |
Get research like this in your inbox
The week’s research that mattered, in five minutes. Joined by 2L+ investors.
When traders use it
- Ahead of events expected to move prices sharply, such as results, budgets or policy decisions.
- When implied volatility is low compared with the move expected.
Risks and costs
- The price must move more than the total premium for the strategy to profit.
- If the event passes and price stays put, time decay and a fall in implied volatility both reduce the value of both options. Often the premium has already priced in the expected move.
- The short version, the short straddle, collects the premium but has unlimited loss on a big move.
Risk note. Strategies that sell options can lose far more than the premium received, and margin requirements apply. SEBI studies have found that roughly nine in ten individual traders in equity derivatives lost money, mostly after costs. See risk management in options trading and transaction costs. Prices below are per unit of the underlying, so multiply by the lot size for rupee amounts. Examples use illustrative Nifty prices and ignore brokerage, taxes and margin.
Related: long strangle and ITM, ATM and OTM options. See the full options strategies guide.
Is your portfolio built for what’s coming?
Get a free AI-powered review of your holdings — risk, overlap and quality in minutes.
Frequently Asked Questions
What is a long straddle?
Buying a call and a put at the same strike and expiry to profit from a large move in either direction.
What is the maximum loss in a long straddle?
The total premium paid, which occurs if the price expires exactly at the strike.
How do you calculate straddle breakevens?
Add the total premium to the strike for the upper breakeven and subtract it for the lower one.
When does a long straddle lose money?
When the underlying moves less than the total premium, or when time decay and falling implied volatility erode both options.
This article is for education only and is not investment advice. Indicator readings describe past price behaviour and do not predict future returns.